TradingKey - Micron Technology (MU) is up 5.00% on Tuesday and at $1,096.16 after a four day winning streak. The company is set to report fiscal fourth quarter results on September 30. Micron has reported record revenues in the previous quarter. The company also reported 84.9% non-GAAP gross margins. Additionally, the data center segment reporting strong numbers. For the upcoming quarter, the company also projected strong numbers. However, there are concerns whether the company can report strong margins, given the tight memory supply and the ongoing labor dispute in Taiwan.
September 30 Earnings Are the Immediate Catalyst
Micron has formally notified the markets that it will report fiscal fourth quarter 2026 results on September 30.
With regard to the guidance, Management expects revenue in the range of $49 billion to $51 billion. Non-GAAP gross margin is expected at approximately 86%. Additionally, Non-GAAP EPS is expected to be in the range of $30 to $32.
For the investors, the key question is whether the results will reflect continued strength in the average selling prices of memory and gross margins.
Q3 Shows the Scale of the Memory Upcycle
Micron's Q3 report showed revenues of $41.46 billion, a massive increase from the $23.86 billion in Q2 and $9.30 billion in Q3 of the previous year.
Micron's Q3 report also showed non-GAAP EPS of $25.11, with a non-GAAP gross margin of 84.9%, and an operating cash flow of $25.39 billion.
After $7.1 billion of net capital expenditures, adjusted free cash flow was $18.3 billion.
It is impressive to see Micron capture and convert this current memory cycle into immense gross margins and cash cycles.
Data Center Is Driving the Earnings Mix
Micron’s Q3 report breaks out the Data Center segment revenues as follows: $11.52Bn from Core Data Center and $13.77Bn from Cloud Memory. Both segments improved from Q2 and had improved gross margins (which were 87% and 83% respectively). Additionally, the company is shipping HBM4 in high volume for Nvidia's Vera Rubin platform and has sent qualification samples to multiple other end customers. The company is also developing HBM4E, with volume production expected in calendar 2027. Also, Micron has its G9-based PCIe Gen6 high-performance SSD in high-volume production and has begun shipping its separate 245TB QLC data-center SSD. Overall, I see the company’s strategy of leveraging AI infrastructure rather than Mobile and PC memory cycles as a positive.
Strategic Customer Agreements Could Improve Visibility
According to Micron, longer term Strategic Customer Agreements (SCAs) provide more certainty in demand and supply planning.
Micron has announced agreements with Anthropic and Ford. Management mentioned 16 such agreements on the Q3 conference call.
The planning benefit of these agreements is acknowledged; however, Micron has not disclosed the financial terms of either the Anthropic or Ford agreements. I will not speculate on the financial benefit of these agreements.
If a greater reliance on SCAs provides stability to Micron’s memory chip pricing and allows for more long-term supply planning, it would improve the memory chip industry.
The 512GB DDR5 Module Adds Another AI Catalyst
On September 15, Micron demonstrated the world’s first 512GB DDR5 RDIMM.
These high capacity modules operate at up to 9,200 MT/s and consume more than 60% less operating power than four 128GB DDR5 RDIMMs.
Since volume production is not expected until the second half of 2027, we should not expect a meaningful impact to Micron’s near-term financial results.
Given the growing number of AI workloads, high capacity memory modules for servers will become even more strategic.
Taiwan Labor Risk Is the Main New Operating Concern
The potential loss of operations at Micron's Taiwan facilities from a labor dispute poses the greatest short-term risk to Micron's operations.
Micron's Taoyuan union and management failed to reach an agreement in mediation over profit sharing, and the union plans to hold a strike vote in early October. While a strike has not been called, the potential for disruption to Micron’s operations in Taiwan is increasing.
Micron operates other fabs in Taiwan that produce DRAM and other memory products. An interruption in Micron's production in Taiwan could affect the global memory market. With limited supplies of memory products, even a temporary disruption to Micron's production in Taiwan could increase prices.
Valuation Still Looks Low Relative to Current Earnings
Micron’s stock price has increased this year and is continuing its uptrend, but earnings have increased even more. Given Micron’s recent performance, the stock currently trades at roughly 7.1 times forward earnings.
Micron has a rerate potential. In the current environment of elevated demand for semiconductors used in AI, Micron could realize high gross margins. However, if additional capacity is built, Micron’s gross and operating margins could contract.
Micron Technical Analysis: MU Breaks $1,045 as Bulls Target $1,112
Micron's most recent closing price is $1,096.16, slightly above its chart price at $1,094.62. Its 1-hour chart remains strongly bullish. This is thanks to its recent breakout above the important resistance level at $1,045.05, as well as the bearish trend line.
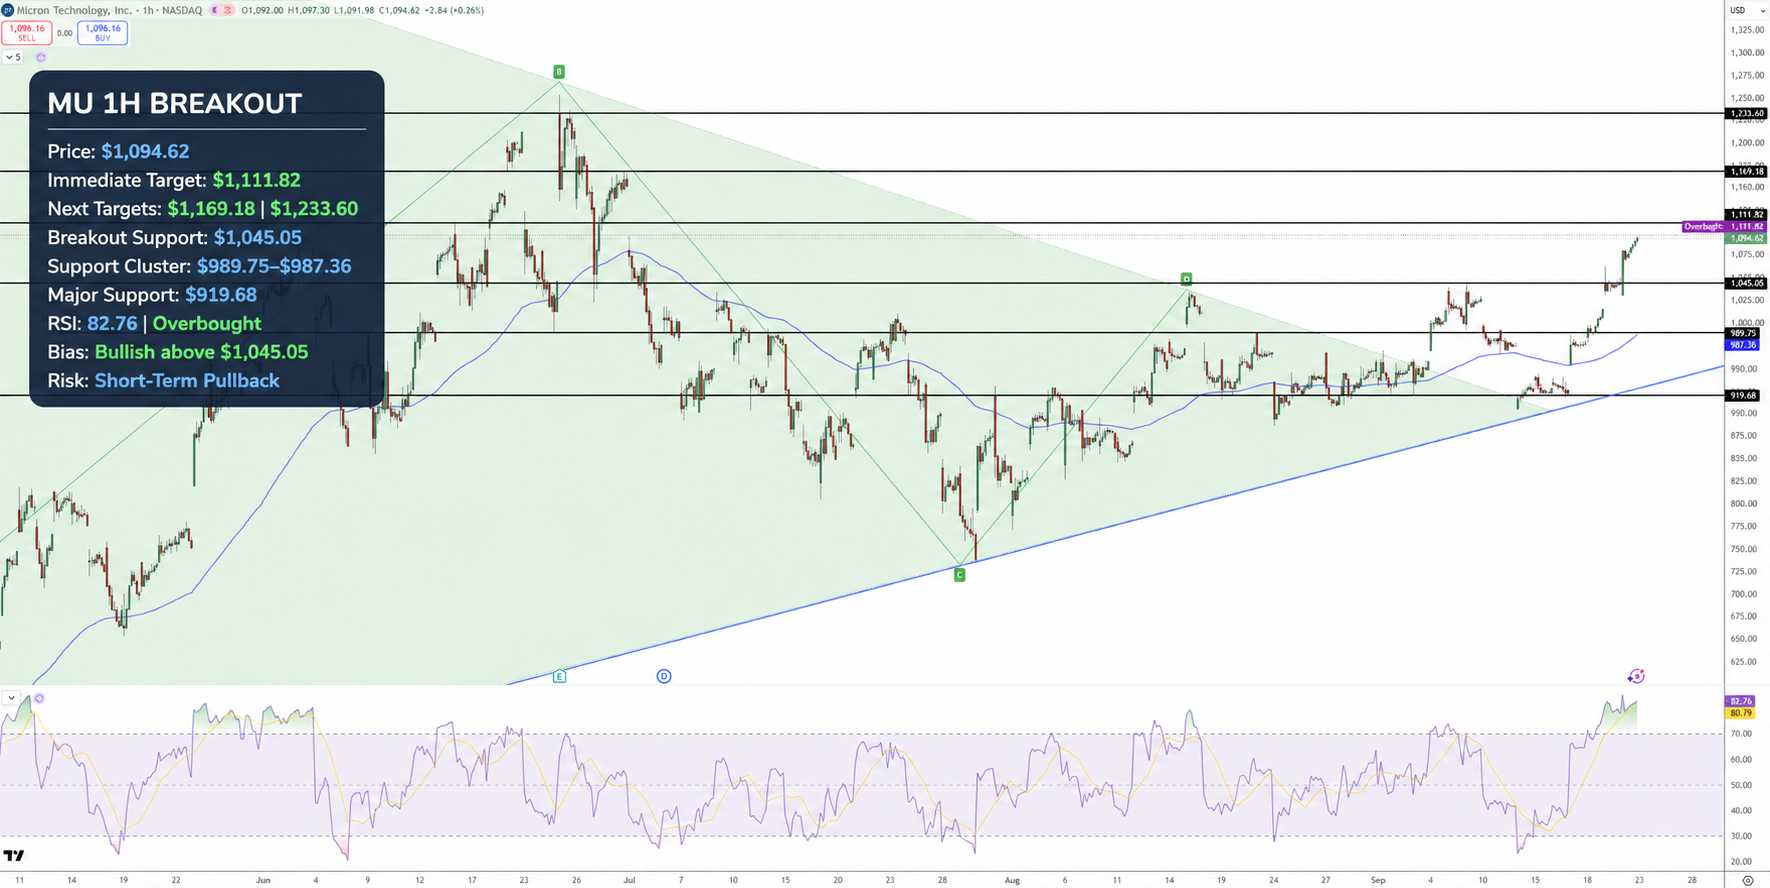
Micron Stock Price Chart - Source: Tradingview
Micron's Relative Strength Index (RSI) is currently at around 83. This not only indicates that the stock is considerably overbought, but also that a minor pullback is possibly in the cards.
In the 1-hour chart, the next important resistance level lies at $1,111.82. A breakout and close above this level would open the way to the $1,169.18 level and the larger bearish trend line.
The important support levels lie at $1,045.05 and at $989.75 and $987.36. These support levels lie near Micron's moving average on the chart. A break below $1,045.05 would likely lead to a move lower to the next support at $919.68.
I expect Micron to continue to trade higher, so long as it trades above $1,045.05. However, given RSI is currently above 80, a minor pullback would be considered normal. My base case outlook is still bullish and targeting moves toward $1,233.60 as long as price stays above $1,045.05.
Why is Micron stock in focus now?
Micron Technology will announce its fiscal Q4 2026 results on September 30. The company expects between $49 billion and $51 billion in revenues, a gross margin in the range of 86%, and non-GAAP EPS in the range of $30 to $32. Given the expectations, the Street is generally positive.
What level confirms a stronger MU breakout?
Traders will look for evidence that buyers broke the resistance level at $1,111.82. If so, the next price target becomes $1,169.18. Traders will also consider a move below the price of $1,045.05 as a breakdown in the current up-trend.
Bottom Line
Micron’s strong Q3 results positions it well in the semiconductor market. As the only major U.S.-based DRAM maker and a supplier already shipping HBM4 in high volume, its gross margins should continue to expand.
MU is facing some risks including the labor tensions at its Taiwan operations, which could lead to a disruption in wafer supply. Additionally, memory pricing remains strong amid tight supply, although future price normalization as capacity expands could cause margins to compress. From a valuation perspective, MU is still somewhat undervalued, and it should trade in the low to mid $1,000s.
Find out more
Comments