TradingKey - On Monday (September 21) US Eastern Time, futures on the three major US stock indexes rose across the board in pre-market trading as high-level US-China talks released positive signals. Meanwhile, Brent crude fell for the fourth consecutive trading day, temporarily easing market concerns about energy prices driving inflation.
As of press time, Nasdaq 100 futures rose 1.04%, S&P 500 futures gained 0.67%, and Dow 30 futures climbed 0.89%.
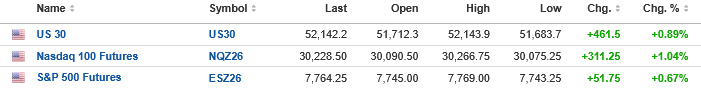
Source: Investing
In commodities, gold (XAUUSD) fell slightly, trading near $4,350/oz; silver (XAGUSD) hovered around $66/oz. A recovery in risk sentiment diminished some safe-haven demand.
International oil prices extended their decline, with WTI crude futures (USOIL-F) pulling back to around $93/barrel, while Brent crude futures (UKOIL-F) dropped to near $101/barrel. Supply concerns cooled down, and Brent crude logged a fourth straight day of losses, easing market worries over persistently rising energy inflation.
In cryptocurrencies, Bitcoin (BTCUSD) rebounded sharply to around $85,000, driving crypto-related stocks broadly higher.
Market Movements
Greenland-concept stocks surged across the board in pre-market trading. U.S. President Donald Trump announced that the U.S. has reached a security agreement with Denmark and Greenland, securing a long-term role in local security affairs and planning to expand its military deployment. Driven by this, Greenland Energy (GLND) soared about 163% in pre-market trading, Greenland Mines rose roughly 120%, and Critical Metals (CRML) gained around 31%.
Market expectations suggest that an expanded U.S. presence in Greenland could bring more political support, infrastructure investment, and financing opportunities to local mining and energy projects. However, the agreement announced so far does not include direct funding, permits, or commercial arrangements for the aforementioned companies.
PulteGroup (PHM) plunged over 15% in pre-market trading. The U.S. 30-year mortgage rate topped 7% again, while the 10-year Treasury yield approached 5%, with rising homebuying costs further dampening housing demand. Several institutions recently lowered their price targets for the company. Among them, Wells Fargo cut its price target from $150 to $145, Truist reduced its target from $145 to $136, and Seaport Research issued a "Sell" rating with a $100 price target.
Novo Nordisk (NVO) fell 7% in pre-market trading. The company raised its full-year outlook, expecting the maximum decline in sales and profit this year to be around 6%, compared with a previously projected drop of up to 12%. However, second-quarter sales of oral Wegovy came in at 3.22 billion Danish kroner, missing market expectations of 3.27 billion Danish kroner and disappointing investors regarding the growth momentum of its weight-loss drugs.
Warner Bros. Discovery (WBD) rose over 7% in pre-market trading. According to reports, Paramount is in advanced talks with the California Attorney General on concessions regarding the acquisition deal, hoping to resolve antitrust lawsuits filed by California and 11 other states.
Potential settlement conditions include a $1.5 billion investment in film and television production. If a final agreement is reached between the two parties, it will help remove a major regulatory hurdle facing the transaction.
MicroStrategy (MSTR) rose over 6% in pre-market trading. As Bitcoin prices recovered, the company's unrealized profit on its Bitcoin holdings expanded to approximately $5.02 billion, after having previously logged an unrealized loss of about $10 billion. Executive Chairman Michael Saylor posted a chart of the company's holdings on platform X with the caption "A little more orange," sparking market speculation that MicroStrategy may have ended its two-week hiatus from buying Bitcoin.
Accenture (ACN) gained over 6% in pre-market trading. Anthropic will partner with Accenture to conduct AI safety evaluations, with both parties planning to invest at least $1 billion over the next five years. The collaboration includes establishing an independent safety evaluation team within Anthropic to perform external testing on frontier AI models. The partnership is non-exclusive, and Accenture may also collaborate with other AI developers in a similar manner in the future. Meanwhile, Deutsche Bank raised its price target for Accenture from $136 to $175 while maintaining a "Hold" rating.
Intel (INTC) rose about 5.4% in pre-market trading. According to reports, the company is partnering with AUO to deploy Micro LED advanced packaging technology, targeting markets including co-packaged optics (CPO) and high-density compute integration. As AI data centers demand increasingly higher bandwidth and energy efficiency, CPO is regarded as a vital technology pathway for next-generation high-speed interconnects. This collaboration will combine Intel's advanced packaging capabilities with AUO's display technology, further strengthening its AI infrastructure layout.
Alibaba (BABA) rose over 1% in pre-market trading. The company will hold its 2026 Apsara Conference in Hangzhou from September 22 to 24 under the theme "Intelligence Goes Beyond." Citi expects the conference to unveil new developments in Qwen model upgrades, MaaS platform infrastructure, T-Head AI and CPU chips, enterprise AI agents, as well as robotics and wearable devices. Alibaba may also reiterate its targets of investing 380 billion yuan over the next three years and reaching $100 billion in external cloud revenue by fiscal year 2031.
Market News
Google fined €403 million for location data violations. The Irish Data Protection Commission stated that Alphabet's (GOOGL) Google violated relevant regulations in how it processed user location data across Web & App Activity and Location History, imposing a €403 million fine.
Regulators noted that users may not have been fully aware that their location data was being used for ad targeting or inferring interests, thus losing effective control over their personal data. This marks the fourth-largest fine issued by the authority since the EU's General Data Protection Regulation (GDPR) took effect.
Jensen Huang rebuts "AI doomsday" theory again. Nvidia (NVDA) CEO Jensen Huang stated that the probability of AI destroying the world before 2030 is zero, and the industry should not slow down but rather accelerate innovation as much as possible. Meanwhile, he also emphasized the importance of safety, believing that companies should not rush to release products when they are not fully ready or carry security risks. His view advocates accelerating AI development while controlling potential risks through engineering and testing measures.
Nasdaq 100 Index quarterly rebalancing takes effect. SpaceX's (SPCX) weighting in the Nasdaq 100 Index will increase from approximately 1.28% to 2.82%. With a market capitalization now exceeding $2 trillion, SpaceX has become the seventh-largest company in the Nasdaq 100 Index by market value. This adjustment will narrow the gap between its market size and index weight, potentially bringing demand for additional allocations from passive index funds.
Morgan Stanley bullish on SpaceX and Tesla partnering on physical AI. Morgan Stanley believes SpaceX and Tesla (TSLA) can share computing power, satellite connectivity, energy infrastructure, robotics, and manufacturing capabilities to jointly capitalize on physical AI opportunities. The firm expects SpaceX's terrestrial computing power to reach 4.9 GW by the end of 2027 and increase to 15.3 GW by the end of 2031, maintaining an "Overweight" rating and a $300 price target on SpaceX, while assigning a $400 price target to Tesla.
SoftBank plans to issue over $11 billion in high-yield bonds. SoftBank Group (SFTBY) plans to issue high-yield bonds totaling over $11 billion, which could become one of the largest junk bond deals in history. Among them, the U.S. dollar bond issuance is about $10 billion with maturities of 3.5 years, 5.5 years, and 7.5 years, respectively, while the euro bond issuance is €1 billion. Proceeds will be used in part to fund SoftBank's third $10 billion investment in OpenAI, as well as for general corporate purposes.
Key Data and Events Preview
At 8:30 a.m. ET, the U.S. releases the August Chicago Fed National Activity Index.
Find out more
Comments