TradingKey - Nu Holdings (the parent company of Nubank) closed at $12.35 on September 29, 2026, up 0.98% for the day. On September 28, 2026, it fell 10.01% on news that Nu is in preliminary talks to purchase the British digital bank Monzo. While Nu Bank is doing well, with record profits and other positive metrics, the question becomes, will opening new markets help Nu Bank even more? Monzo Bank’s operations are in the UK and Ireland, while it is pursuing broader European expansion.
Monzo Talks Add a New Capital-Allocation Question
Nu Bank is considering purchasing Monzo, according to the Financial Times. Monzo is reportedly valued between £8-10bn. The deal could be a cash and/or stock deal. There is no merger agreement, other financing options are being considered by Monzo, and the terms of the deal are unknown. So from Nu Bank’s perspective, should they be considering a Monzo acquisition? It is likely Nu Bank management is considering the deal, but from an ownership perspective, is the potential return from a Monzo acquisition better than other opportunities Nu Bank has in markets like Brazil, Mexico, and the US?
The Selloff Shows Investors Want More Discipline
Nu fall’s 10% on Sep. 28 after reports of preliminary Monzo acquisition talks. Recovering slightly on Sep. 29, it ended the day well below the $13.59 close from Sep. 25. Investors may be worried about management’s focus on organic growth with several markets, and a large international acquisition. Management’s focus on organic growth is warranted, given the investments and expansion initiatives in the U.S. Additional international expansion is probable, and with a large international acquisition, there is potential for further growth, though it could increase the company’s business complexities.
Q2 Delivered Record Profitability
Nu reported record results for Q2 and has a solid outlook for the remainder of the year. Results were above Street expectations and it provides a good entry opportunity for long term investors. With several expansion initiatives and strategic focus, the company may benefit from an acquisition to support the focus on core activities. The board and management remain disciplined, with the focus on organic growth.
Nus Q2 results show continued business momentum. Gross revenue increased by 39% year over year on an FX-neutral basis to approximately $5.9 billion. Net profits improved by 49% to approximately $1.1 billion. Return on Equity improved to 33%. Nu clearly has moved beyond its customer growth story phase. The company is clearly a profitable and large scale operation. Existing and new customers realize that the company’s existing business is a profitable and large-scale operation. Nu can afford to make an acquisition.
Customer Growth and Monetization Remain Strong
Nu increased customer additions by 4 million to 139 million. Monthly activity rate improved to 83.5% from 83.2% last year. Monthly average revenue per active customer improved to $17.1 from $12.5 last year. The company continued its focus on adding customers and has improved monetization. Improved monetization and high activity rates show customers generated more revenue while remaining active with the company. High levels of activity and monetization give investors comfort for potential further international operations.
Credit Quality Is the Main Operating Risk
Different trends affected Nu's credit metrics during Q2. The ratio of loans that are 15-90 days past due, fell to 4.8%. Loans that are 90 days past due and longer, increased to 6.9%. The improvement in short-term delinquencies was attributed to seasonality by management. Longer-term delinquencies were attributed largely to seasonal migration from earlier delinquency buckets. As of Q2, total credit portfolio was $39.4 billion. Total deposits were $45.3 billion. Risk adjusted net interest margin was 12.4%. I am focused on credit quality. As the credit portfolio is stretched to higher risk segments, so the operating risk increases. Strong credit underwriting should allow for disciplined expansion of higher risk lending, and help support earnings. Longer term delinquencies should be closely monitored as they negatively impact the expansion outlook, even if top line is positively impacted.
The U.S. Launch Is a Confirmed Growth Initiative
Nu started serving the US market on September 10. Nu is offering deposit accounts, money transfers (domestic and international) and a credit card (with no annual fee) through its partnership with Lead Bank. Lead Bank provides the banking services under the partner-bank model. Nu has preliminary conditional approval from the OCC for a national bank charter, while Federal Reserve and FDIC approvals remain pending. Currently, Nu is using the partner bank model for its US operations. Using the partner bank model allows Nu to enter the US market quickly and gives Nu time to build its other banking operations. Since the partner bank allows Nu to offer banking services quicker, it allows Nu to focus on other areas of the business before meaningfully generating income.
Nu Global Broadens the International Platform
Nu is simultaneously expanding into other markets with its cross-border money transfer product, Nu Global. With Nu Global, Nu is able to provide customers transactions in over 35 countries. Similar to other neobanks, Nu provides a multi-currency, high-yield digital account. With Nu Global, deposits can be converted into stable coins that are pegged to the U.S. dollar and the euro. To succeed with its global expansion, Nu must ensure it products don't negatively impact the margins of its core, domestic, banking operations.
Valuation Is More Accessible After the Selloff
At the recent close, Nu fetched around 16.7 times and 12.6 times trailing and forward earnings, respectively. These multiples are more modest than many high-growth Fintech stock multiples. With the lower valuations, the upside potential has increased. The average analyst price target is $18.69. These price targets are not official guide posts. In my opinion, given the recent valuation multiples, the risk premium has improved as long as the company continues to have disciplined capital allocation. This means M&A activity would have to slow to maintain the recent valuation multiples.
Upcoming Catalysts Will Test the Strategy
Nu’s next earnings release is currently estimated for November 12. Nu will also host its first investor day on December 8. These events should provide more information on Nu’s international business, and clarify the company’s capital allocation policy. In general, I will become bullish on Nu if it maintains strong risk adjusted returns and NIM while not growing too aggressively. I will become bearish if 90+ day loan delinquencies increase, and especially if the company makes a large, dilutive acquisition, and provides little justification.
Nu Holdings Technical Analysis: NU Breaks Rising Channel as $12.23 Support Faces Pressure
Nu Holdings ended its trading day at $12.35. The stock broke down sharply from its rising channel where it previously traded and recoverd from May. I like to trade from the levels of support and resistance. The previous area of support at $13.45 broke along with the channel, and was subsequently followed by a break of the 10 day and 20 day moving averages.
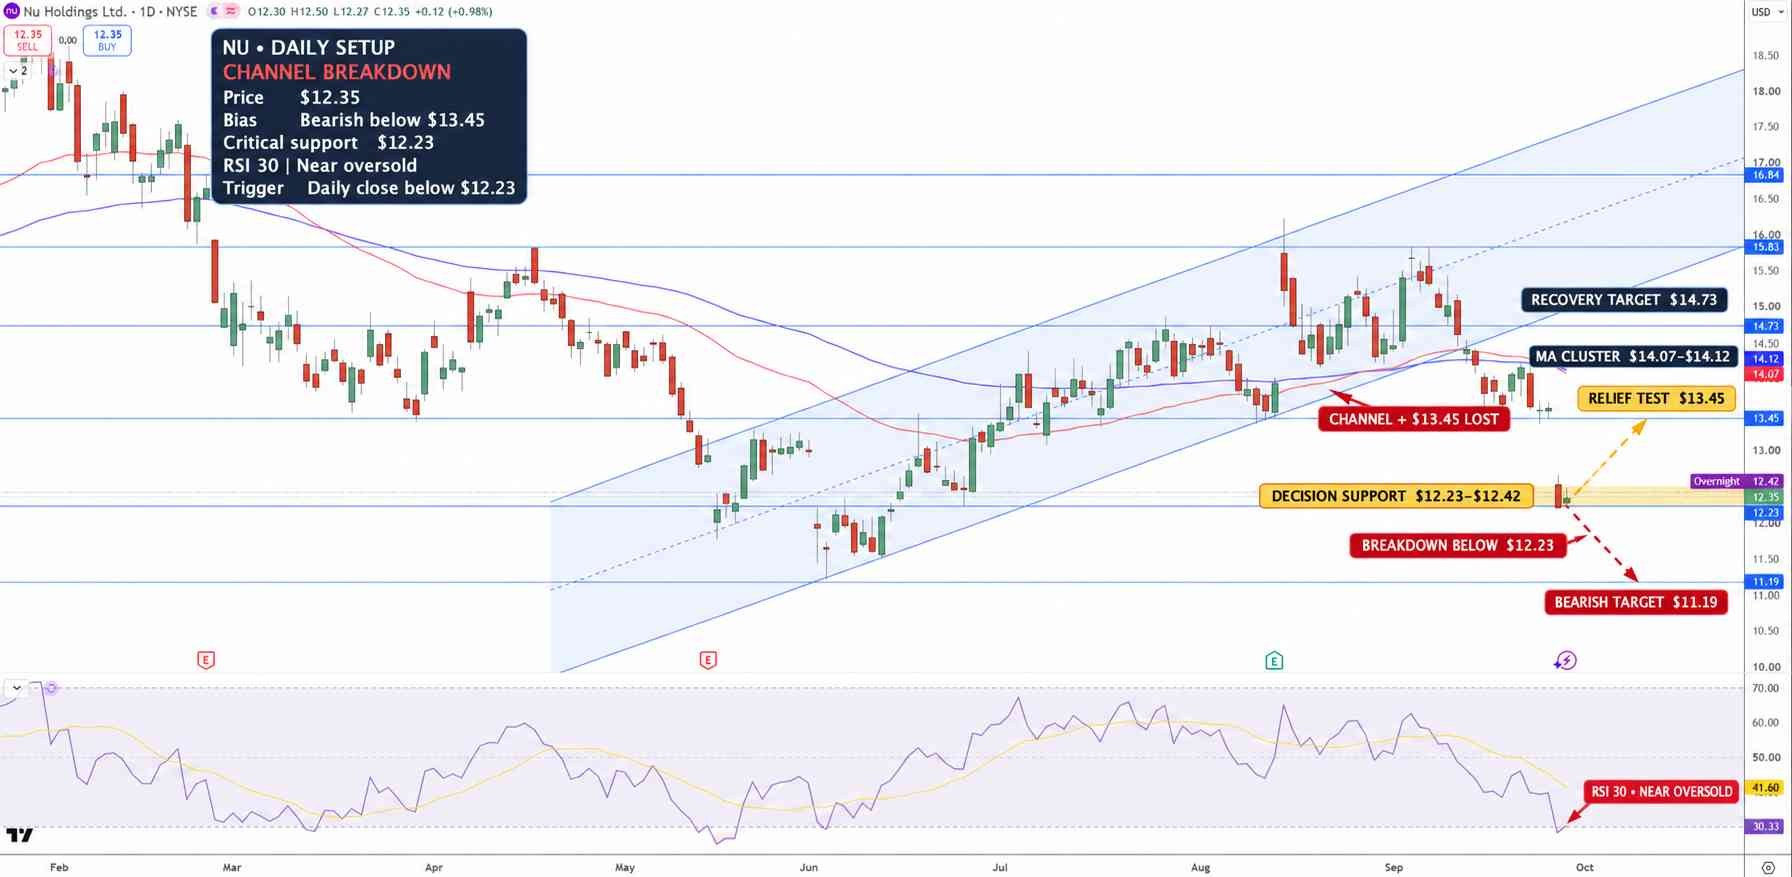
Nu Holdings Stock Price Chart - Source: Tradingview
This previous support area is now a target area for selling pressure. The moving averages are falling, and hence are bearish. The Relative Strength Index (RSI) is about 30, and is thus near oversold territory. This shows that the stock may be due for a bounce. The immediate support level is at $12.23. A breakdown of this level would indicate further downside for the stock to the next major support level of $11.19.
The first major area of resistance for the stock is at $13.45. Above this level, the moving-average cluster would be the next area of focus at $14.07 and $14.12. A recovery through this area would bring $14.73 into focus. I would view a break above $13.45 as bullish, however the near-oversold condition of the RSI indicates that a retest of $12.23 may be likely.
Why is Nu Holdings stock in focus now?
Nu is capturing investor attention for a couple of reasons. First, its reported preliminary talks to acquire Monzo is shedding light on how the company will allocate its capital at a pivotal moment as it strengthens its business in the U.S. and South America and reporting blockbuster financial results. Lastly, investors are concerned about risk, acquisition costs, and dilution.
What level confirms a stronger NU recovery?
A lasting move above the $13.45 level would be a bullish sign and bring the $14.07-$14.12 area into focus, followed by $14.73. If the price of the stock falls and breaks below the $12.23 level, more downside is likely in the near-term.
Bottom Line
While risks are present with Nu Holdings, that doesn't take away from the positive nature of the company. For the quarter ending in June 2026, the company reported record breaking financial results and improved monetization. From a purely technical analysis, the stock is likely to fall to the $11.19 level if it trades below the $12.23 level. A close below the $12.23 level is likely.
Find out more
Comments