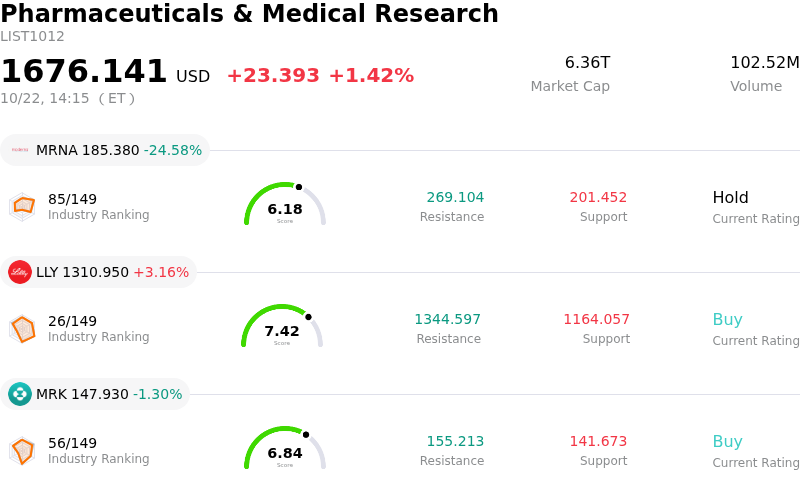
AstraZeneca PLC (AZN) moved up by 3.04%. The Pharmaceuticals & Medical Research sector is up by 1.42%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Moderna Inc (MRNA) down 24.58%; Eli Lilly and Co (LLY) up 3.16%; Merck & Co Inc (MRK) down 1.30%.
What is driving AstraZeneca PLC (AZN)’s stock price up today?
AstraZeneca experienced positive trading momentum driven by a major regulatory catalyst in its rare disease portfolio. The U.S. Food and Drug Administration granted accelerated approval for Ultomiris (ravulizumab) to treat adults with primary immunoglobulin A nephropathy at risk of rapid disease progression. This clearance expands AstraZeneca's commercial footprint into high-risk renal disorders, addressing a target market of over 200,000 U.S. patients. Investor enthusiasm was further supported by additional pipeline updates, including positive late-stage trial readouts for Tezspire in eosinophilic esophagitis and the U.S. availability of Zegfrovy for non-small cell lung cancer.
The expansion of key therapeutic indications reinforces AstraZeneca's multi-pillar growth strategy across rare diseases, oncology, and biopharmaceuticals. Institutional interest remains anchored in the company's strong pipeline productivity, which helps offset generic competition and revenue erosion from legacy treatments. With third-quarter financial results on the horizon, investors are assessing how recent regulatory milestones will contribute to long-term growth targets. Market observers highlight that steady pipeline execution provides fundamental support to earnings forecasts and reinforces high-margin portfolio diversification.
Intraday price movement exhibited notable volatility as market participants evaluated immediate commercialization prospects against ongoing clinical trials required to secure full regulatory approval. AstraZeneca continues to trade at a competitive valuation relative to sector peers, attracting institutional capital seeking defensive growth exposure. Overall, the stock's upward trajectory reflects sustained market confidence in AstraZeneca's core R&D execution and commercial expansion strategy.
Technical Analysis of AstraZeneca PLC (AZN)
Technically, AstraZeneca PLC (AZN) shows a MACD (12,26,9) value of 2.941, indicating a buy signal. The RSI at 65.858 suggests neutral condition and the Williams %R at 1.062 suggests overbought condition. Please monitor closely.
Fundamental Analysis of AstraZeneca PLC (AZN)
AstraZeneca PLC (AZN) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $58.74B, ranking 8 in the industry. The net profit is $10.22B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $210.32, a high of $255.24, and a low of $158.00.
More details about AstraZeneca PLC (AZN)
Company Specific Risks:
- Phase III Clinical Trial Setbacks and Litigation Exposure: Recent late-stage clinical failures, including the HICKORY trial for efzimfotase alfa in rare bone disease and the CARDIO-TTransform study for Wainua in ATTR cardiomyopathy, threaten key growth drivers needed for management's $80 billion 2030 revenue ambition while triggering shareholder class-action litigation investigations.
- Analyst Downgrades and Early-2030s Patent Cliff Vulnerabilities: Institutional sell-side downgrades, including HSBC lowering the stock from Buy to Hold, highlight an unfavorable risk-reward balance ahead of key catalyst readouts (SERENA-4 and AVANZAR) and amplify concerns over revenue replacement as major exclusivity patents expire in the early 2030s.
- Accelerated Approval Reliance and IgAN Market Competition: The FDA's accelerated approval of Ultomiris for IgAN relies on interim surrogate endpoints (proteinuria reduction) without yet proving long-term preservation of kidney function, leaving the drug commercially exposed against established competitive treatments from Novartis and Travere Therapeutics.
- Capital Allocation and Licensing Execution Risks: Multi-billion-dollar strategic commitments into external drug candidates, including the $2 billion investment in Summit Therapeutics for ivonescimab, elevate execution and financial risk if combination immuno-oncology trials fail to deliver superior overall survival metrics.
Find out more
Comments