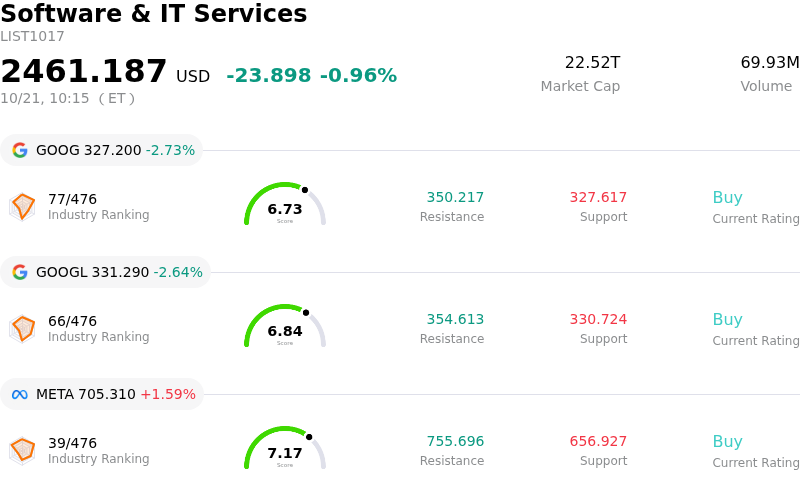
Alibaba Group Holding Ltd (BABA) moved down by 3.58%. The Software & IT Services sector is down by 0.96%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Alphabet Inc Class C (GOOG) down 2.81%; Alphabet Inc Class A (GOOGL) down 2.71%; Meta Platforms Inc (META) up 1.45%.
What is driving Alibaba Group Holding Ltd (BABA)’s stock price down today?
Alibaba Group Holding experienced downward momentum as broader market sentiment toward Chinese technology and consumer equities faced renewed pressure. Institutional investors continue to approach China-focused ADRs with heightened caution, driven by lingering concerns over macroeconomic recovery momentum in the domestic market and intense competitive dynamics within the e-commerce sector. This macro uncertainty has created a challenging backdrop for Chinese internet leaders, leading some asset managers to trim equity exposure during periods of sector-wide rebalancing.
The primary fundamental factor weighing on investor confidence remains the financial pressure stemming from the company's aggressive capital expenditures. Alibaba has committed massive funding toward its multi-year artificial intelligence infrastructure roadmap, cloud computing expansion, and next-generation consumer hardware initiatives. While these strategic investments reinforce the company's long-term competitive positioning in cloud services and generative AI models, they have simultaneously compressed near-term margins and reduced free cash flow generation. Investors are increasingly focusing on the execution timeline and return on capital, expressing skepticism over when these capital-intensive projects will meaningfully contribute to bottom-line profitability.
Additionally, industry dynamics and supply chain friction present ongoing structural hurdles. Despite strong demand for advanced computing hardware to power its proprietary AI ecosystem, supply caps and geopolitical export controls continue to limit access to high-performance semiconductors, constraining the speed of cloud scaling. Concurrently, institutional portfolio adjustments reflect a split consensus, where long-term value-oriented investors acknowledge low valuation multiples while shorter-term funds remain wary of ongoing profit dilution. Until clearer signs of consumer spending stabilization and tangible returns on AI investments emerge, the stock remains vulnerable to heightened intraday volatility and selling pressure.
Technical Analysis of Alibaba Group Holding Ltd (BABA)
Technically, Alibaba Group Holding Ltd (BABA) shows a MACD (12,26,9) value of -0.045, indicating a sell signal. The RSI at 37.401 suggests neutral condition and the Williams %R at 98.520 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Alibaba Group Holding Ltd (BABA)
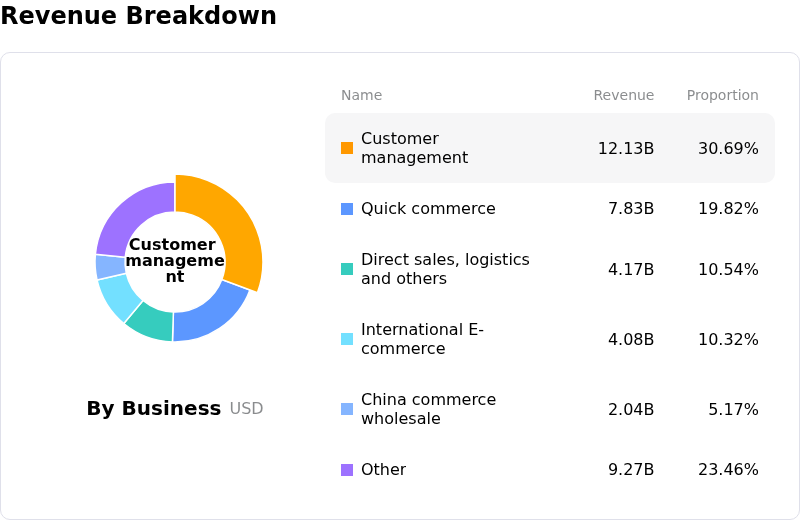
Alibaba Group Holding Ltd (BABA) is in the Software & IT Services industry. Its latest annual revenue is $144.14B, ranking 5 in the industry. The net profit is $14.91B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $184.28, a high of $220.10, and a low of $95.00.
More details about Alibaba Group Holding Ltd (BABA)
Company Specific Risks:
- Capital Expenditure & Margin Compression: Aggressive capital commitments to artificial intelligence infrastructure and data center expansion—including major regional computing initiatives—continue to drain free cash flow and depress near-term operating margins.
- Securities Litigation & Regulatory Sanctions: BABA faces sustained investor pressure from active U.S. securities class-action lawsuits concerning non-disclosure of its status under U.S. National Defense Authorization Act "Chinese military company" listings and allegations related to third-party AI model distillation.
- Analyst Downgrades & Earnings Misses: Institutional research desks have trimmed price targets and lowered ratings to Hold following consecutive quarterly earnings misses and persistent uncertainty surrounding earnings recovery timing.
- Core E-Commerce & Domestic Headwinds: Slowing consumer spending in mainland China combined with aggressive market-share competition from rival platforms is forcing elevated marketing expenditures while dampening primary retail growth.
Find out more
Comments