TradingKey - Microsoft (MSFT) will report its first-quarter fiscal 2027 financial results after the U.S. market close on October 28 ET. As cloud computing demand remains strong and enterprises accelerate the deployment of artificial intelligence applications, the market is waiting for Microsoft to deliver its new quarterly growth report card.
FactSet data shows that Wall Street currently expects Microsoft's first-quarter adjusted earnings per share to be approximately $4.71 and revenue to be around $90.62 billion, up roughly 14% and 16.7% year-over-year, respectively. Microsoft previously provided quarterly revenue guidance of $89.85 billion to $90.95 billion. The market consensus is already near the upper end of the guidance range, meaning actual results and forward outlook could both impact investors' assessment of the company's growth prospects.
At the operational level, the growth rate of Azure cloud services, the commercialization progress of Microsoft 365 and Copilot, as well as capital expenditures and free cash flow, will be the three main focus areas for this earnings report.
Can Azure Growth Beat Guidance to Become Main Earnings Highlight
Microsoft previously projected that Azure's first-quarter revenue would grow 44% to 45% in constant currency, up from 43% in the prior quarter. Morgan Stanley was even more optimistic, forecasting that actual growth could reach around 47%, while Oppenheimer estimated it at approximately 46%.
The momentum behind Azure's growth stems from both traditional cloud computing and AI workloads. Enterprises continue to migrate applications and data to the cloud, while demand for AI model inference, AI agent applications, and related infrastructure is also rising.
Morgan Stanley (MS) believes Microsoft's competitive advantage in the enterprise cloud service market remains prominent. Its CIO survey showed that Microsoft leads Amazon in enterprise IT budget share growth. As companies increase public cloud and AI-related spending, Azure remains well-positioned to benefit.
However, strong demand does not necessarily mean revenue will accelerate at the same pace. Microsoft has previously stated multiple times that data center capacity constraints limit Azure's ability to meet customer demand. Therefore, investors will not only focus on whether quarterly growth meets expectations, but also pay attention to when new computing power comes online and whether Microsoft can sustain its growth momentum in coming quarters.
Morgan Stanley estimates that Microsoft will add approximately 3.25 gigawatts of new data center capacity in fiscal year 2026, which is expected to further increase to about 4.25 gigawatts in fiscal year 2027. As new capacity is gradually brought online, Microsoft is expected to absorb more of the demand previously constrained by capacity. However, whether the new capacity can translate into revenue in a timely manner still depends on facility deployment progress, customer adoption, and operational efficiency.
In addition, Microsoft expects first-quarter revenue for its Intelligent Cloud segment to be between $40.95 billion and $41.25 billion, representing a year-over-year growth of about 33% to 34%. If Azure's growth accelerates further, the cloud business is expected to remain the core growth driver for Microsoft overall.
Copilot Commercialization and AI Investment Returns Determine Growth Quality
Beyond Azure, the commercialization progress of Microsoft 365 and Copilot will determine whether Microsoft can generate more high-margin AI revenue outside of infrastructure.
As of the end of the previous fiscal year, Microsoft 365 Copilot's paid seats exceeded 30 million, with approximately 10 million added in the fourth quarter. In the first quarter, the key focus will be whether enterprise customers continue to expand deployment rather than remaining in the small-scale trial stage.
Microsoft has integrated Chat, Cowork, Code, and Autopilot agents into a unified Copilot experience and is attempting to expand from simple per-seat subscriptions to pricing models based on user call volumes and workloads. Over the long term, this is expected to boost revenue contribution per customer; in the short term, however, Copilot's growth still primarily relies on an increase in paid seats and customer upgrades from Microsoft 365 E3 to higher-priced plans such as E5 or E7.
The company expects Microsoft 365 Commercial Cloud revenue to grow by approximately 17% on a constant-currency basis in the first quarter. If Copilot adoption rates rise and premium security and data management suites sustain growth, Microsoft could maintain high margins in its software business despite rising AI inference costs.
The flip side of AI investment is steadily rising infrastructure costs.
Microsoft previously projected that capital expenditures in the first quarter of fiscal 2027 would exceed $50 billion, significantly higher than the roughly $41 billion recorded in the previous quarter. The company aims to meet cloud and AI demand by continuously building data centers and expanding compute capacity, but investors will also weigh whether the additional spending can yield corresponding revenue and profit growth.
Morgan Stanley estimates that Microsoft's overall gross margin for fiscal 2027 could decline by about 2 percentage points year-over-year to 65.8%, while its operating margin is expected to remain around 46.6%. The firm believes that AI infrastructure expansion will put pressure on gross margins, but expense controls and operational efficiency gains can partially offset the impact. Microsoft previously noted that it has reduced the time required for data center equipment to transition from deployment to revenue generation, which helps improve the utilization efficiency of newly added compute capacity.
Wall Street's Highest Price Target at $725
Ahead of the earnings release, several institutions have updated their outlooks on Microsoft. Morgan Stanley maintained its $600 price target, believing that Azure growth, Copilot commercialization, and infrastructure efficiency improvements will support Microsoft's long-term profitability. Oppenheimer raised its price target from $570 to $625 while maintaining a positive rating, and Truist also raised its price target from $575 to $600.
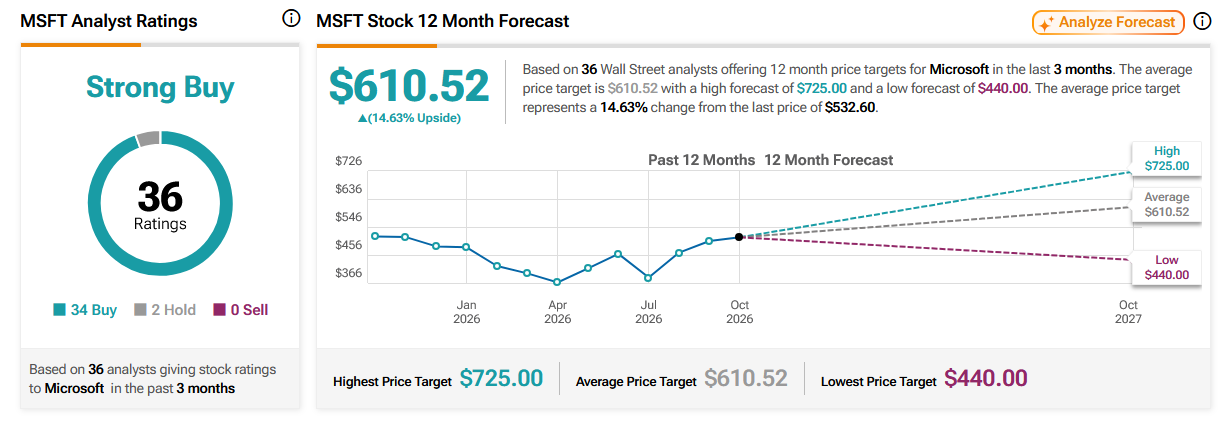
According to TipRanks, the average price target from 36 analysts covering Microsoft over the past three months is approximately $607.87, with a high target of $725 and a low of $440, representing an overall rating of "Strong Buy".
Source: TradingView
From a valuation perspective, Microsoft still faces a balance between growth expectations and investment costs. If Azure's growth rate meets or exceeds Wall Street expectations, paid adoption of Copilot continues to expand, and capital expenditures gradually translate into revenue, the market may have greater confidence to pay a premium for Microsoft's AI business. Conversely, if cloud growth falls short of expectations, or heavy investments fail to bring corresponding improvements in cash flow, the stock price may come under pressure.
Find out more
Comments