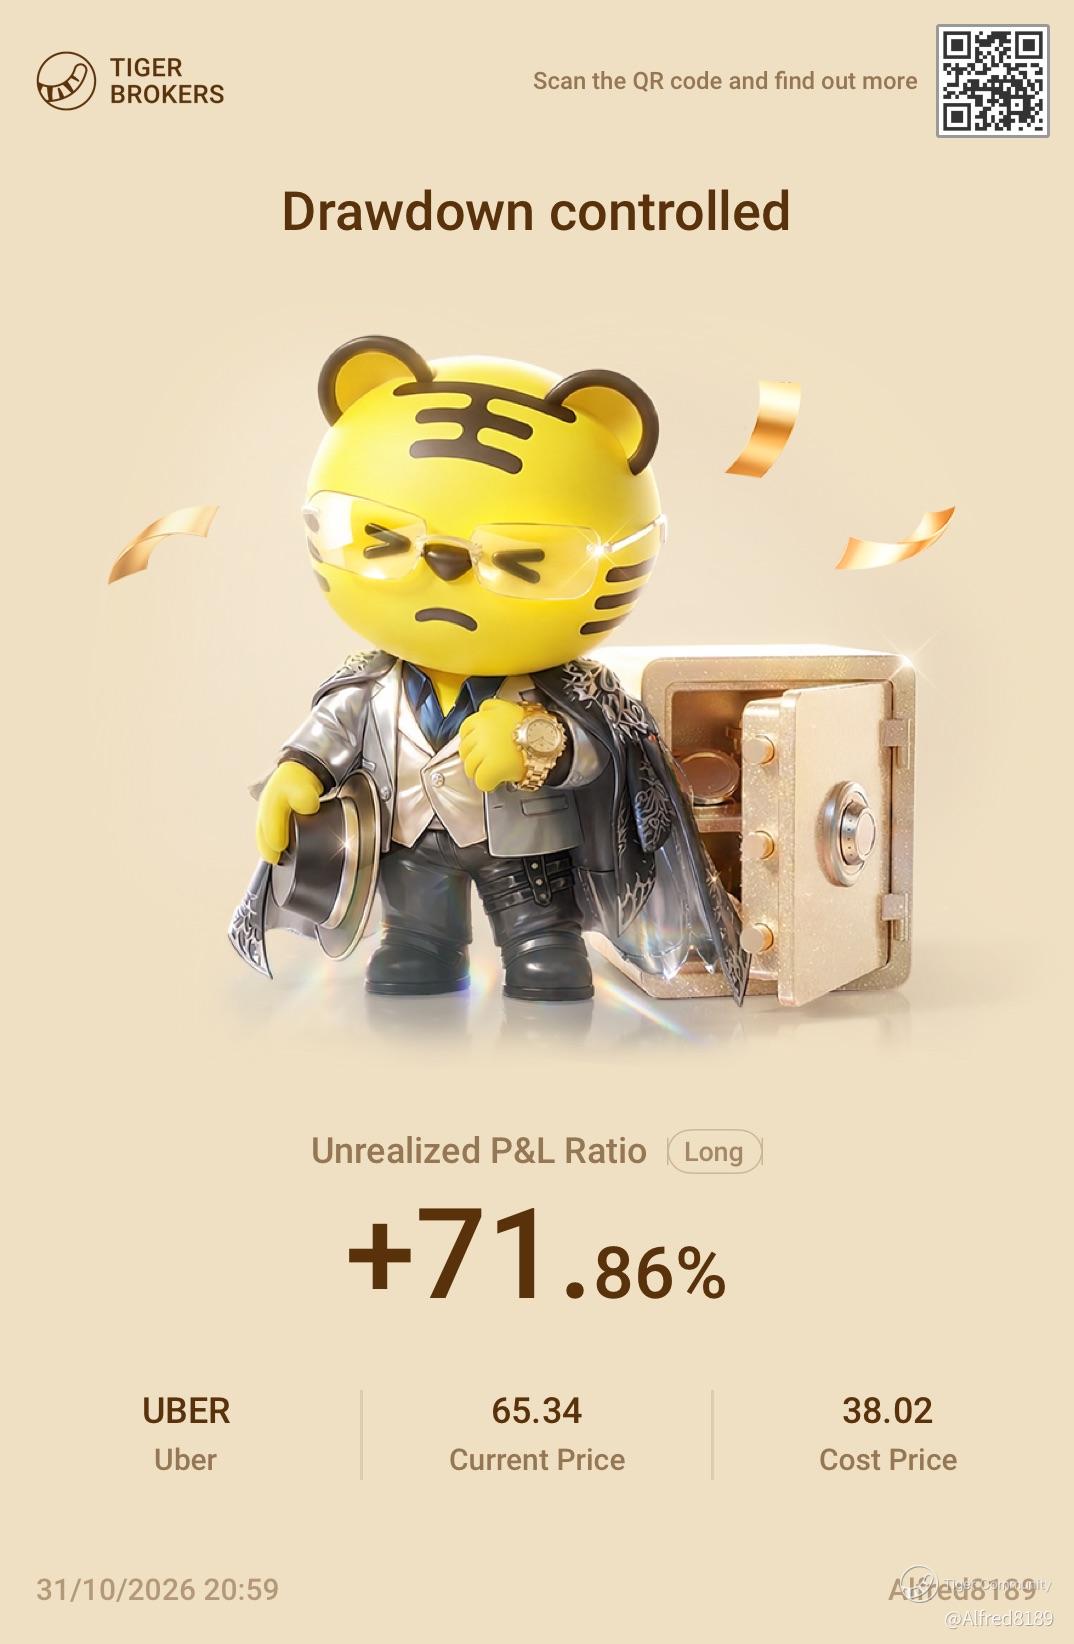
Uber remains an attractive long-term investment, supported by strong growth in its mobility and delivery businesses. Its Q2 2026 results showed 22% growth in Gross Bookings and 35% growth in non-GAAP EPS, demonstrating improving profitability and operational efficiency. The company also generated substantial free cash flow, strengthening its financial position. However, competition, regulatory challenges and the potential impact of autonomous vehicles remain key risks. Overall, I view Uber positively, with solid growth potential. I would consider accumulating shares gradually while monitoring valuation and upcoming earnings performance.
$Uber(UBER)$
Winning Trades
Share your positions with us! This is a column where you can find the winning trades of our fellow tigers. There probably are a few potential opportunities that you may have overlooked.
Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Comments