Weekly Roundup 1. The Real Focus of the FOMC Isn't the Rate Move. It's the Treasury Yield Curve. Markets have largely priced in a 25-basis-point hike, so whether asset prices reprice sharply in the near term will hinge on how the Fed frames its future rate path and inflation outlook. The 10-year Treasury yield is closing in on 5%, and a decisive break above that level would weigh on both stocks and gold through three channels: valuation discounting, funding costs and risk appetite. What markets are really waiting on is whether long-term yields have peaked. 2. Beneath a Calm Surface, US Stocks Show Signs of Technical Fatigue. Market breadth is fading fast: only about 28% of NYSE-listed stocks are trading above their 20-day moving average, and the equal-weight S&P 500 has slipped be
MNQmain (Micro E-Mini Nasdaq 100 - main 2612)
Please go to Tiger Trade for futures detailsDownload APP
Macro Strategy Weekly: 4 Fed Paths Decide Gold and Stocks Tonight! Which Strategy Wins?
Macro Strategy Weekly: 4 Fed Paths Decide Gold and Stocks Tonight! Which Strategy Wins?
How to Trade FOMC Night: Can the Fed Contain Long-Term Yields Without Breaking Equities?
This week’s FOMC meeting will set the near- to medium-term rhythm for markets. But the key issue is not simply whether the Fed raises rates; it is how Treasury yields at the front end and long end of the curve will be repriced. The 10-year Treasury yield is now approaching—or has already touched—the sensitive 5% threshold. Markets are concerned both that further increases in long-dated yields could crush richly valued assets and that excessive policy tightening could push up front-end rates and quickly hit equities. In our view, four possible meeting outcomes could unfold this week. All ultimately revolve around the tug-of-war between the front end and the long end of the yield curve, although the implications for individual asset classes differ across scenarios. A Tense Yield Environment
How to Trade FOMC Night: Can the Fed Contain Long-Term Yields Without Breaking Equities?
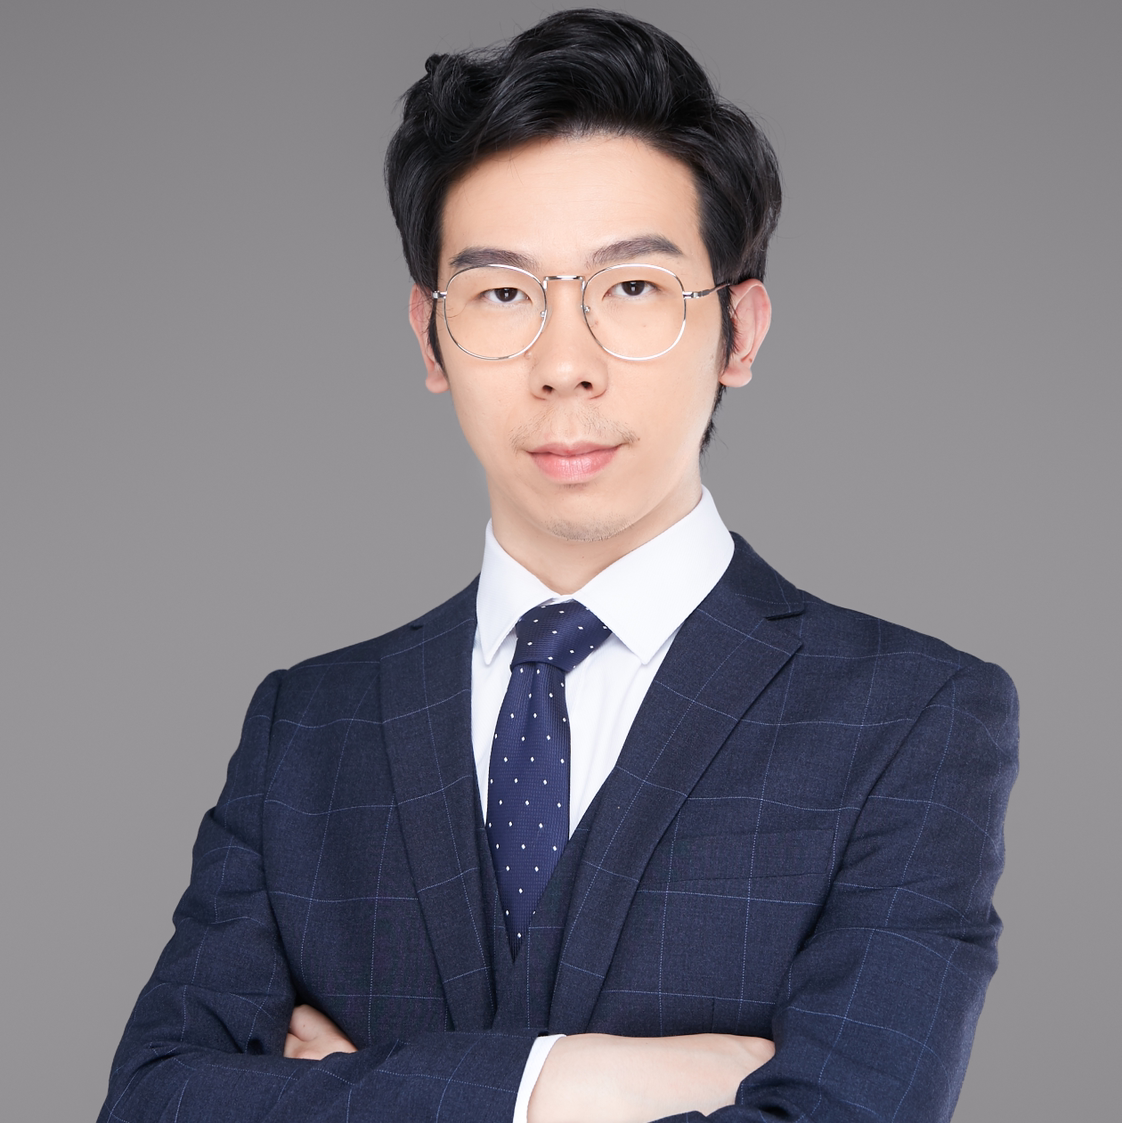
How to Reposition After Taking Profits: A Practical Framework for Futures Rollovers and ETF Trading
After holding the positions for more than two months, our long EUR and WTI crude oil trades both generated positive returns last week. With a Federal Reserve rate hike drawing near, new trade setups may emerge at any time. Many investors still have questions about several key issues. This week, we will use the current market backdrop to review the main considerations and provide a practical framework. Managing Futures Contract Rollovers One of the most common questions concerns futures contract rollovers. Because we frequently run swing trades and some positions are held for relatively long periods, changes in the front-month or most-active contract are sometimes unavoidable. Since physical delivery is generally not a practical option, the choices are usually limited to the following: Sett
How to Reposition After Taking Profits: A Practical Framework for Futures Rollovers and ETF Trading
FOMC Preview: Watch Key Levels in U.S. Equities; Stay Alert to a Pullback in Commodities After Rally
Last week’s CPI release brought market expectations for a Federal Reserve rate hike into much sharper alignment. Following the euro area’s earlier rate increase and a 0.3% month-over-month rise in core CPI, markets are now pricing in roughly a 90% probability that the Fed will raise rates in September. Although core CPI came in marginally above expectations, the overall reading was not excessively strong. In particular, core CPI has not accelerated significantly even with oil prices approaching USD 100 per barrel. The market also generally expects the Fed’s tightening path to remain relatively gradual. As a result, a rate hike this week is largely priced in. Conversely, if the Fed unexpectedly leaves rates unchanged, the decision could be interpreted as a positive surprise and potentially
FOMC Preview: Watch Key Levels in U.S. Equities; Stay Alert to a Pullback in Commodities After Rally
Could Rate Hike Uncertainty Keep Markets Range-Bound? Three Ways to Track the Key Assets
Last night, in a futures livestream on the Tiger platform, I shared my latest views on the outlook for gold, Bitcoin, and offshore RMB amid expectations for higher interest rates. The core of this session was how to assess the direction of these assets through cross-asset correlations, while also covering trading strategy execution and adjustments to moving average parameters. Those who were unable to attend may watch the replay of our video course here: >>> 空前的高收益率壓力下,為什麼比特幣的低位機會卻很值得關注? Next, I will summarize the key information and trading-related views from the session, so that readers who did not have time to join can quickly unders
Could Rate Hike Uncertainty Keep Markets Range-Bound? Three Ways to Track the Key Assets
Weekly Valuation Watch: AI Capex Rises as Cash Flow Falls Behind, Can Returns Justify the Risk?
Introduction: Markets Hold Firm as Rate Sensitivity Rises From August 31 to September 4, U.S. stocks moved as investors weighed geopolitical risks, higher oil prices, volatile global bond yields and a stronger jobs report. SPY gained 0.41% for the week, suggesting that risk appetite remained intact. However, market swings grew sharper. On September 4, August nonfarm payrolls rose by 162,000, well above forecasts, while unemployment held at 4.1%. As a result, Treasury yields and the dollar climbed, prompting investors to price in a greater chance of further Fed tightening. $标普500(.SPX)$ $标普500ETF(SPY)$ $SP500指数主连 2609
Weekly Valuation Watch: AI Capex Rises as Cash Flow Falls Behind, Can Returns Justify the Risk?
Macro Strategy Weekly: China’s Energy Rebound Lifts Global Yields: Options for Range-Bound Markets
Macro Strategy Weekly China’s Rebounding Energy Demand Is Pushing Global Yields Higher: What Is the Best Options Strategy for Navigating a Range-Bound Market? Weekly Strategy Summary The key focus for markets this week is not to make a directional bet on any single asset. Rather, it is to monitor how the yen, crude oil, global bond yields, the U.S. dollar, and U.S. equities establish new inter-market linkages. The key takeaways from this week’s report are as follows. $Japanese Yen - main 2609(JPYmain)$ $WTI Crude Oil - main 2610(CLmain)$ $E-mini Crude Oil - main 2610(QMmain)$
Macro Strategy Weekly: China’s Energy Rebound Lifts Global Yields: Options for Range-Bound Markets
Selling Puts Remains My Preferred Strategy:Will Tokyo Set the Market’s Direction This Week?
The market’s greatest challenge this week is that several seemingly independent trading themes are beginning to interact with one another: the yen has reached a six-month high; expectations of a Bank of Japan rate hike are building; global bond yields are broadly rising; signs are emerging of a rebound in China’s crude-oil demand; and expectations for Federal Reserve policy have once again been unsettled by comments from Donald Trump. When these variables move simultaneously, markets rarely deliver a clean, smooth one-way trend. Instead, they are more likely to enter a high-volatility, range-bound phase marked by repeated swings in both directions. The key variable to watch now is whether the yen can make a further near-term directional break. This matters not only for the U.S. dollar inde
Selling Puts Remains My Preferred Strategy:Will Tokyo Set the Market’s Direction This Week?
Blowout NFP, Trump Pressure, and a Choppy Gold Market: One Strategy to Navigate It!💹📉
Last week’s note highlighted the need for caution around the nonfarm payrolls report. The data had become more difficult to forecast than usual because payroll figures have been revised frequently in recent years, increasing the likelihood of surprises and larger market swings. The result was indeed a blowout: U.S. Department of Labor data showed that nonfarm employment surged by 162,000 in August, far exceeding the market expectation of 55,000. This exceptionally strong report once again disrupted the market’s expectations for Federal Reserve policy. The market had previously scaled back expectations of a September rate hike, but the release put rate-hike expectations back in the driver’s seat. The probability of a Fed rate increase in September has now returned to roughly a 60/40 split.
Blowout NFP, Trump Pressure, and a Choppy Gold Market: One Strategy to Navigate It!💹📉
U.S. Stocks: Will Semis Drag Markets Lower Again? Bitcoin: Escape Hatch or Bomb?
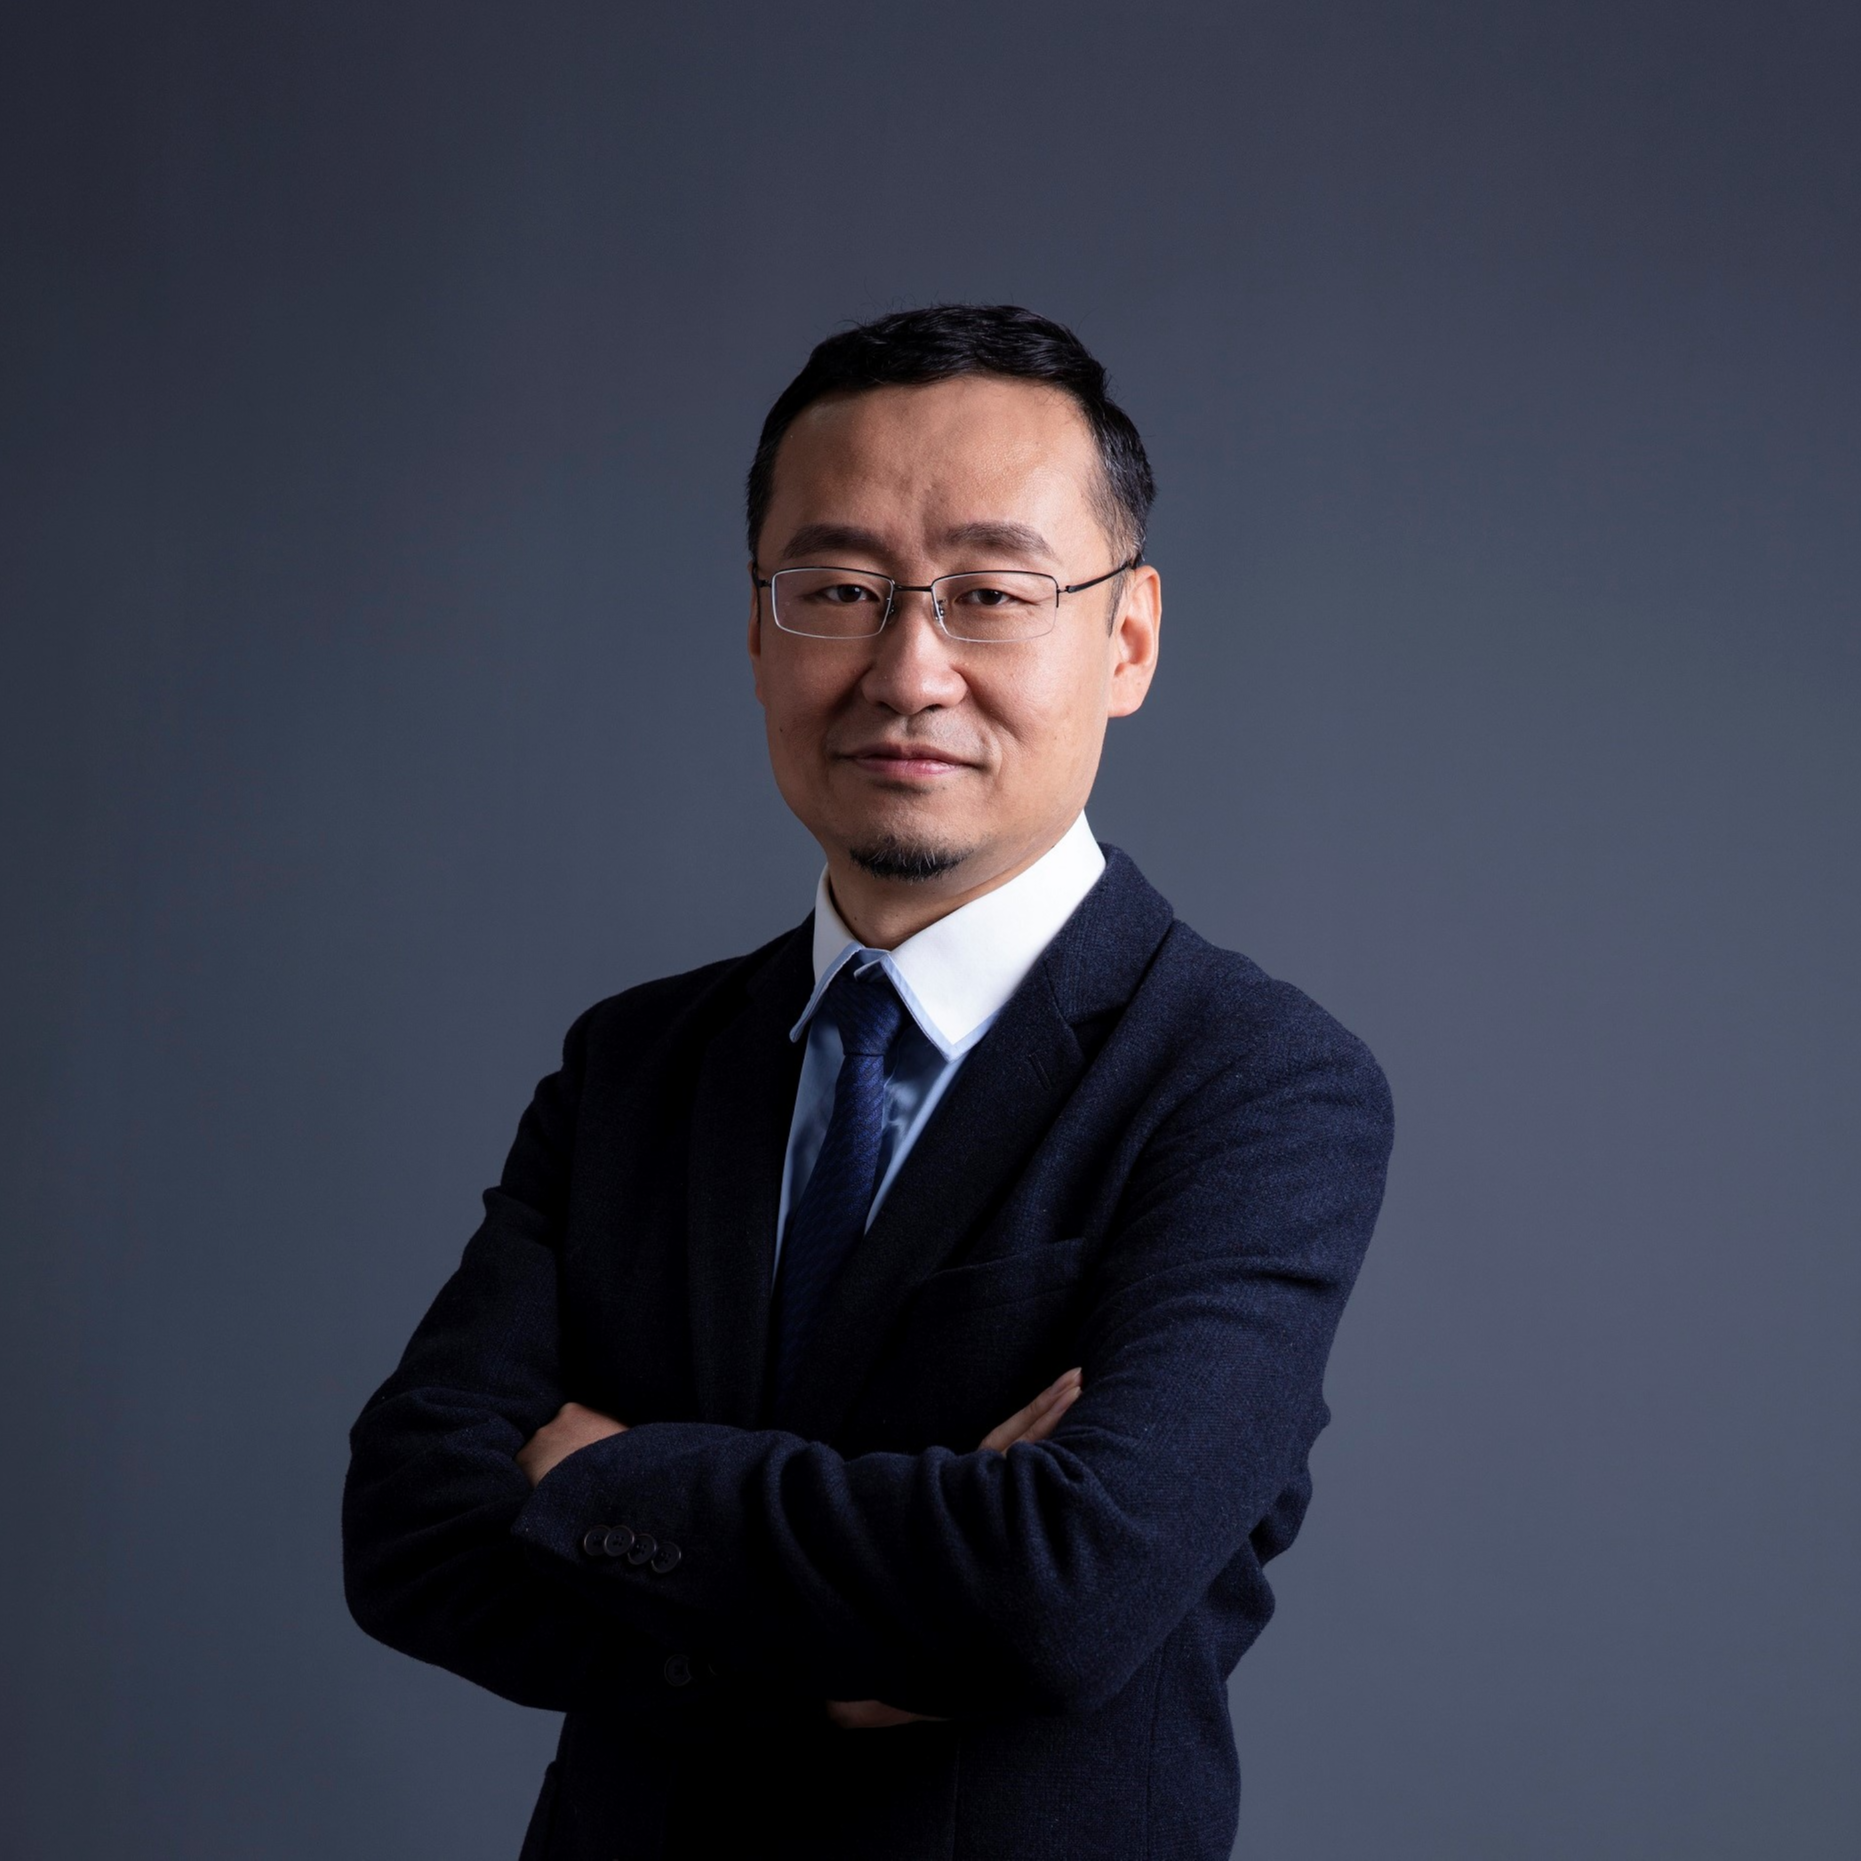
Last night, I hosted a live session on Tiger’s futures platform titled Global Multi-Asset Allocation Strategy. The session covered global macro conditions, U.S. equities, gold, and Bitcoin, with a focus on the market’s key tensions, potential risks, and corresponding trading ideas. For those who were unable to attend the live session, the replay is available here >>> U.S. Stocks: Will Semis Drag Markets Lower Again? Bitcoin: Escape Hatch or Bomb? Below, I have organized the key information and trading-related views from the session to help readers who did not have time to attend quickly understand my current market perspective. Before that, let me briefly introduce my background. I am currently a contracte
U.S. Stocks: Will Semis Drag Markets Lower Again? Bitcoin: Escape Hatch or Bomb?
Macro Strategy Weekly: VIX Seasonal Spike Incoming,Top Strategy for Choppy Markets
Our Call That Gold and U.S. Equities Had Topped Out in the Near Term Has Been Validated Again Hello everyone, welcome back to the Macro Strategy Weekly. In this weekly report, we regularly select contributors within the community who have relevant professional expertise to share and consolidate their market-strategy views. We also track, on a weekly basis, how those strategy calls have played out. Before turning to this week’s strategy discussion, let us review the results of our previous calls. On July 21 this year, our strategy weekly published an analysis titled: Macro Strategy Weekly: Treasury Bond Purchases Are Bearish for Markets—U.S. Equity and Gold Bulls Should Be Cautious The report received substantial engagem
Macro Strategy Weekly: VIX Seasonal Spike Incoming,Top Strategy for Choppy Markets
Why Sell Puts Still Make Sense Now — And the Big Opportunity Brewing in Equities
The impasse of range-bound trading at elevated levels in the U.S. equity market remains unresolved. On the one hand, September seasonality, defensive positioning by institutional investors, and the potential seasonal tendency for the VIX to rise all suggest that a strong short-term rally is unlikely. On the other hand, robust corporate earnings and the fact that equity-index P/E multiples have not expanded materially are limiting the downside for U.S. equities. My conclusion for the U.S. market over the coming week is therefore as follows: taking all factors into account, U.S. equities are more likely to remain range-bound at elevated levels than to enter a one-way decline. At the same time, we should pay attention to a new opportunity at relatively depressed levels: commodity indices are
Why Sell Puts Still Make Sense Now — And the Big Opportunity Brewing in Equities
Gold’s Correction Arrived as Expected—Will 4,000 Hold as Support?
Late August is typically when the world’s central banks hold a major annual gathering. The Federal Reserve—the “central bank of the world,” as it is sometimes described—is the central figure at the event, and remarks from the Fed Chair are often viewed as a briefing to central banks around the world on the Fed’s policy path. At present, the financial market’s primary concern is whether the Federal Reserve will raise interest rates and, if so, when. That is why Fed Chair Kevin Warsh’s hawkish remarks last week had a significant impact on market expectations. The most direct result was that, following Warsh’s speech in Jackson Hole on August 28, 2026, the interest-rate futures-implied probability of a September rate hike rose from approximately 35% the previous day to nearly 60%. A rate hike
Gold’s Correction Arrived as Expected—Will 4,000 Hold as Support?
Nonfarm Payrolls in Focus: Will Gold Hold as Equity Indices Reassess?
Following last weekend’s Jackson Hole symposium, Fed Chair Kevin Warsh delivered a relatively hawkish message, prompting the market to reassess and reprice the timing of U.S. interest-rate hikes. According to the current FedWatch data, the probability of a rate hike at the end of September is slightly above 50%. This implies that the next round of nonfarm payroll and inflation data to be released next month could play an important role. From a data perspective, the probability of a rate hike surged by nearly 20 percentage points within just one week, driven entirely by Warsh’s remarks rather than by any other major economic data releases. However, based on historical experience, only probabilities above 70% tend to produce near-certain outcomes. With the current probability still below 60%
Nonfarm Payrolls in Focus: Will Gold Hold as Equity Indices Reassess?
Could the U.S. Treasury’s Aggressive Market Support Backfire? Three Ways to Track the Current Market
Last night, in a futures livestream on the Tiger platform, I shared my latest views on the movements of gold, equity indices, and the U.S. dollar following the U.S. Treasury’s announcement on Treasury bond purchases. The core of this session was how to assess, through correlations across different asset classes, whether the market has shifted from a range-bound environment into a new trend phase. Those who were unable to attend may watch the replay of our video course here: >>> Could the U.S. Treasury’s Aggressive Market Support Backfire? Three Ways to Track the Current Market Next, I will summarize the key information and
Could the U.S. Treasury’s Aggressive Market Support Backfire? Three Ways to Track the Current Market
Weekly Valuation Watch:The US Equity Rally Faces a Test? Diverging Flows and Uneven M7 Valuations
This week sits at a key macro inflection point for US equities: the US is set to release important macro data including GDP and PCE, while the Jackson Hole Global Central Bank Symposium will be held over the weekend, where Fed Chair Kevin Warsh’s remarks could provide new guidance for rate expectations. Against this backdrop, Nvidia, a core name in the AI supply chain, will report earnings after the close on Wednesday; its results and guidance will directly test whether elevated capital expenditure can continue to translate into orders and profitability. The confluence of macro data, central bank commentary, and tech leadership earnings makes this week a critical checkpoint for whether the “AI narrative” can continue to support rich valuations. The core issue this week is not the direction
Weekly Valuation Watch:The US Equity Rally Faces a Test? Diverging Flows and Uneven M7 Valuations
Macro Strategy Weekly: Treasury Buybacks, Jackson Hole, and the Key Trend Every Trader Must Watch
This Week’s Highlights 1. The U.S. Treasury will at least double the size of its liquidity-support buybacks for Treasury securities maturing in 10 to 30 years, raising the cap per operation from USD 2 billion to at least USD 4 billion. This measure may help stabilize the long-term bond market temporarily and suggests that the Treasury may be seeking to keep long-term yields near 5%. However, Treasury buybacks are not equivalent to the Federal Reserve purchasing bonds with newly created money through quantitative easing. They more closely resemble replacing long-term debt with short-term debt, and therefore cannot fundamentally eliminate the pressure from high deficits, elevated interest costs, and excessive long-term bond supply. If the market instead questions the government’s ability to
Macro Strategy Weekly: Treasury Buybacks, Jackson Hole, and the Key Trend Every Trader Must Watch
U.S. Equity Technicals Turn Bearish? Several Opportunities Worth Watching (Recent Yield Sharing)
The market did not take long to choose a short- to medium-term direction. Last week, gold and crypto assets both surged, making it clear that the market had entered a new phase of rebound. The previous trading logic can therefore be carried forward naturally, and risk assets are expected to remain resilient through the period before the fourth quarter. The only factor requiring particular caution is the speed of the advance. The logic chain of crypto assets—gold—risk assets changed slightly during last week’s trading. Following the news that the U.S. Treasury would purchase bonds, gold reacted most quickly. However, in terms of both absolute gains and the pace of appreciation, Bitcoin and Ethereum—whose volatility is inherently higher—soon staged a catch-up move and outperformed the earlie
U.S. Equity Technicals Turn Bearish? Several Opportunities Worth Watching (Recent Yield Sharing)
Treasury’s Large-Scale Rescue May Not Be Good? Be Cautious Chasing Gold Higher
While the market remained focused on the probability of a Federal Reserve rate hike, the U.S. Treasury released a surprising announcement last week. The Treasury announced that it would “at least double” the size of its liquidity-support buyback operations for Treasury securities maturing in 10 to 30 years, raising the cap for each buyback from USD 2 billion to at least USD 4 billion. Relative to the USD 31 trillion U.S. Treasury market, this buyback volume is negligible. Nevertheless, the Treasury’s move conveyed several messages to the market. First, long-term bond yields are too high, and the Treasury intends to exert some control over them. Second, Treasury yields around 5% may represent a psychological threshold for the U.S. Treasury; if yields deviate too far from that level, more fo
Treasury’s Large-Scale Rescue May Not Be Good? Be Cautious Chasing Gold Higher
Futures Weekly:Institutions Pile into Energy&Metals as Tight Oil Inventories Risk Premiums
Over the past week, the core narrative shaping global asset pricing revolved around two themes. On the geopolitical front, negotiations between the United States and Iran over the Strait of Hormuz reached an impasse, with both sides engaging in heated exchanges and refusing to yield. According to Bloomberg tanker-tracking data, Middle Eastern crude oil loadings fell from 20 million barrels per day in early July to 12 million barrels per day by the end of July, with the supply disruption shifting from a “risk premium” into a “physical supply shortfall.” On the macroeconomic front, U.S. headline CPI rose 3.4% year over year in July, while core CPI increased 2.5%; month-over-month growth resumed. PPI rose 4.7% year over year, while nonfarm payroll employment unexpectedly declined by 23,000 in
Futures Weekly:Institutions Pile into Energy&Metals as Tight Oil Inventories Risk Premiums